
The Tax Omnibus and its impact on European competitiveness
The proposed Tax Omnibus could reduce administrative burdens, support investment and contribute to a more competitive Single Market. At a recent GDV event in Brussels, participants discussed the challenge ahead: meaningful simplification will depend not only on the rules agreed at EU level, but also on implementation, cooperation between national authorities and the willingness of Member States to accept short-term costs in pursuit of longer-term benefits.
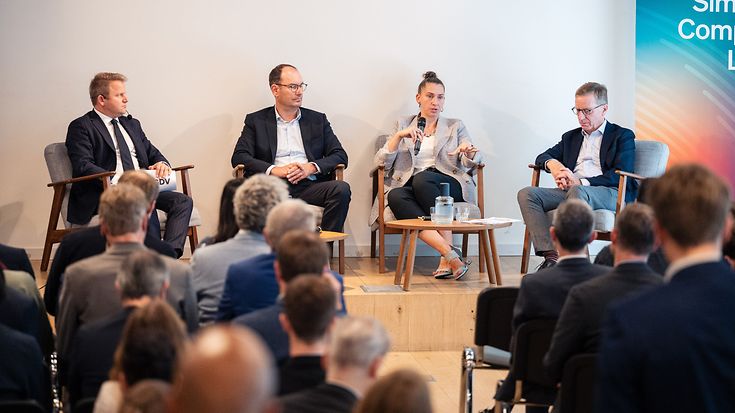
Panellists, from left to right: Florian Wimber (GDV), Holger Engelke (MunichRe), Ioana Diaconescu (European Commission), Prof. Dr. Michael Hüther (German Economic Institute IW)
Simplification as part of the competitiveness agenda
Europe is looking for ways to strengthen competitiveness, encourage investment, and make it easier for companies to operate and grow across borders. Taxation is one part of this agenda, alongside a wider effort to examine whether existing rules remain fit for purpose.
The speakers noted that parts of the tax framework have become increasingly complex over time. Some rules have been in place for many years, while businesses can face overlapping requirements and repeated reporting obligations. Simplification therefore means more than reducing the number of individual rules: it also means ensuring that the overall framework works more efficiently for companies operating within the Single Market.
The Tax Omnibus should not be seen as a solution to all of Europe’s competitiveness challenges. It was described as one element of a much wider economic agenda. Making cross-border investment easier, reducing unnecessary bureaucracy, and improving the functioning of the Single Market will require action in several policy areas.
Reducing duplication without weakening safeguards
A recurring theme was the practical burden created by compliance and reporting requirements. For companies operating across borders, simplifying reporting and eliminating duplication could make a tangible difference.
At the same time, simplification was not presented as an abandonment of safeguards. The discussion stressed the need to maintain rules that address genuine risks, while avoiding a situation in which layers of safeguards themselves become difficult to enforce. The challenge is therefore to find a framework that protects the objectives of the tax system without creating unnecessary complexity.
Digitalisation needs to work across borders
Simpler rules are only part of the answer, but one needs to also focus on how those rules are administered.
Digitalisation can make tax processes more efficient and transparent, but its benefits depend on public authorities being able to communicate with one another. Where national systems do not exchange information effectively, businesses can still face duplication even if reporting itself becomes more digital.
The discussion therefore underlined that administrative modernisation needs to accompany changes to EU rules. Tax administrations do not always develop at the same speed as businesses and markets, and the Tax Omnibus could also provide an impulse for improvements at national level.
For companies operating across the Single Market, this distinction matters: simplification is not only about what businesses have to report, but also about how information is collected, exchanged, and used.
The short-term cost of long-term reform
One of the central difficulties is that simplification can itself require investment. This became clear when the discussion turned to Member States. Governments may recognise the case for reforms that encourage investment and economic growth, while at the same time facing immediate budget constraints and implementation costs.
Participants argued that the benefits of reform may take longer to materialise than the political or budgetary cycle. Measures that make Europe more attractive for investment could ultimately support larger companies, greater economic activity, and higher revenues, but those effects may emerge only over the medium or longer term. This makes the political discussion around reform more difficult, particularly when governments are already operating with limited fiscal room.
This issue returned during the audience discussion, where the possible short-term fiscal costs of simplification were contrasted with benefits that could take several years to become visible. Participants stressed that reform therefore requires a longer-term perspective on investment and fiscal policy.
A first step towards a more competitive framework
For the insurance sector, the Tax Omnibus was broadly discussed as an opportunity to reduce administrative burdens and improve the environment for doing business across borders. At the same time, participants expressed the hope that simplification would go further than the measures currently on the table, including by addressing unnecessary cross-border notification and reporting requirements.
The wider message of the discussion was that simplification should ultimately be judged by what companies experience in practice. Clearer rules, less duplicate reporting, better digital cooperation between authorities, and consistent implementation can all contribute to making the Single Market easier to navigate.
The Tax Omnibus is unlikely to be the end of Europe’s simplification debate. But it can be an important test of whether the ambition to strengthen competitiveness can be translated into practical changes for businesses. As the discussion concluded, the package represents a first step and making that first step work will be essential before further progress can follow.