
Closing Europe's climate insurance protection gap: prevention, resilience, and insurance
As climate-related natural catastrophes become more frequent and costly, Europe faces growing challenges in protecting households, businesses and public finances.
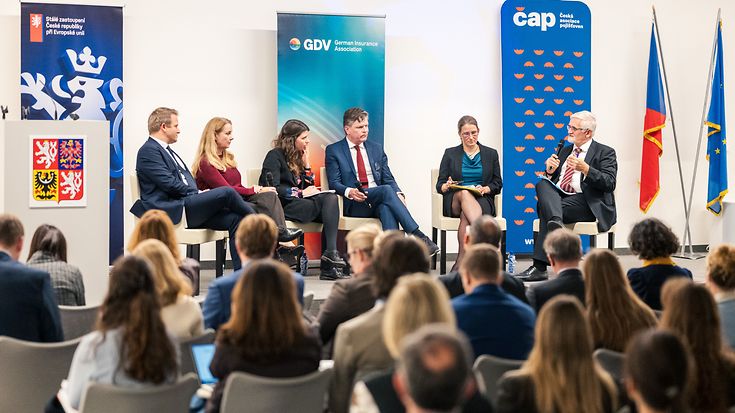
From left to right: Florian Wimber (GDV), Kamila Šimonová (Allianz Insurance Czech Republic), Caoimhe Adams (Munich Re), Patrick Hoedjes (EIOPA), Linda Rousová (ECB), and Jan Dusík (European Commission)
The increasing frequency and severity of natural catastrophes are putting Europe's resilience to the test. Floods, storms, wildfires, and heatwaves can cause significant economic losses, while only a share of these losses is covered by insurance. This leaves households, businesses, and governments exposed to substantial financial risks.
A central message of the discussion was that prevention and insurance should not be seen as alternatives, but as complementary tools. While insurance provides financial protection and supports recovery after disasters, effective prevention can reduce their impact in the first place.
Investments in early warning systems, climate-resilient infrastructure and better risk assessment are therefore essential. The experience of recent floods in the Czech Republic illustrated how preparedness and early warnings can help limit damage. At the same time, the destruction of roads, bridges and other infrastructure highlighted the potentially high costs and long recovery periods associated with natural catastrophes.
The discussion also emphasised the need to integrate climate risks into long-term planning. This includes considering natural catastrophe risks when developing infrastructure, making investment decisions and determining where new buildings should be constructed.
Climate resilience is also an economic priority
The economic consequences of climate-related disasters extend well beyond the immediate physical damage. Natural catastrophes can disrupt economic activity, affect businesses, and create financial pressures that persist long after an event.
Research discussed during the event highlighted how extreme weather events can have lasting effects on regional economic output. Insurance can help mitigate these consequences by enabling households and businesses to recover more quickly, thereby supporting broader economic recovery.
Against this background, the European Commission's Integrated Framework for Climate Resilience was welcomed as an important step towards a more coordinated European approach. The framework seeks to strengthen the assessment and management of climate risks across different policy areas, taking into account the need for cooperation between European institutions, national governments and other stakeholders.
Participants stressed that climate resilience requires long-term investment and should be considered an economic and financial planning priority. Strengthening resilience can help reduce future losses while creating better conditions for investment and insurability.
Making insurance more accessible and affordable
Another key challenge is increasing insurance coverage against natural catastrophes. Despite growing awareness of climate risks, many households and businesses remain uninsured or insufficiently protected.
The discussion highlighted several factors contributing to this protection gap, including limited awareness of individual risks, uncertainty about insurance costs, and affordability concerns. Making insurance products easier to understand and providing transparent information about coverage and pricing could help consumers make more informed decisions.
Insurers can also play an important role in encouraging prevention. Risk-based pricing and appropriate financial incentives can help households and businesses better understand their exposure and take measures to protect their properties.
However, affordability remains a central concern, particularly in areas facing high levels of climate risk. Participants discussed how public-private partnerships could contribute to making insurance more accessible, despite this not being a silver bullet.
Different national approaches, including mandatory insurance schemes, were also considered. While such arrangements can help expand coverage and distribute risks more widely, the discussion showed that there is no universal solution. Differences between national insurance markets, risk profiles and existing protection systems need to be taken into account.
Better data and stronger cooperation are essential
Reliable data and risk modelling emerged as fundamental requirements for both effective prevention and the development of suitable insurance solutions.
Understanding how climate risks are evolving, where they are concentrated and how they could affect different sectors is essential for public authorities, insurers and financial institutions. Improved data sharing and the use of digital tools can support more accurate risk assessments and better-informed decisions.
At the European level, the Climate Insurance Alliance announced by the European Commission was also discussed as a potential means of bringing stakeholders together and building a stronger common foundation for addressing climate risks. Its development could provide an opportunity to improve cooperation, promote better-informed approaches to risk management and explore ways to increase insurance coverage.
At the same time, climate risks do not stop at national borders. Cross-border challenges, such as river flooding, require coordination between EU Member States and a more integrated approach to risk management.
The discussion therefore underlined the importance of cooperation at European, national and local levels. Public authorities, insurers, financial institutions, and other stakeholders all have a role to play in strengthening resilience.
Public-private partnerships could be particularly valuable in addressing risks that cannot be managed by the insurance sector alone. While insurers can provide financial protection, risk expertise and incentives for prevention, governments remain essential in areas such as infrastructure planning, adaptation measures and addressing affordability challenges.
Towards a more resilient Europe
Closing Europe's climate insurance protection gap will require more than increasing the number of insurance policies. It means reducing risks before disasters occur, ensuring that financial protection is accessible and creating the conditions for faster recovery when losses cannot be prevented.
The European Commission's Integrated Framework for Climate Resilience provides an opportunity to advance this agenda. However, translating European ambitions into effective measures will require continued cooperation, investment, and clear responsibilities across the public and private sectors.
Ultimately, the discussion highlighted that a more resilient Europe depends on combining effective prevention with broad and affordable insurance protection. Neither governments nor insurers can address the growing challenges of climate change alone. Strengthening cooperation and making better use of risk data, financial incentives, and shared expertise will be essential to protecting European citizens, businesses, and economies.